Stanford Financial is campaigning to open the Defence Home Ownership Assistance Scheme home loan panel, so that ADF members and veterans can use their subsidy with any accredited lender at the same rate any other borrower would be offered. The full case, the figures and the running record of the campaign now sit on our DHOAS reform page. This post is a short summary of what has happened so far.
The problem in short
DHOAS pays an eligible member a monthly subsidy into their home loan account, but only if that loan sits with one of three lenders the Commonwealth appointed in 2008: NAB, Australian Military Bank and Defence Bank. With that little competition, the rates on offer can sit as much as 100 basis points above the broader market for the same product. On a typical $830,000 owner-occupier loan that is around $156,000 in additional interest across the 25-year subsidy period.
Access is the second problem. Each panel lender applies its own credit policy, so a veteran who does not fit any of the three is shut out of the scheme entirely. We act for veterans missing more than $1,000 a month in subsidy for that reason alone, which is over $317,000 across the maximum subsidy period.
What has happened so far
- 11 May 2026. Logan Stanford wrote to the Treasurer, the Shadow Treasurer and the crossbench setting out the case for opening the panel under section 78 of the DHOAS Act, with rate parity written into the deeds of agreement on the same terms Housing Australia applies to the First Home Guarantee. Read the press release (PDF).
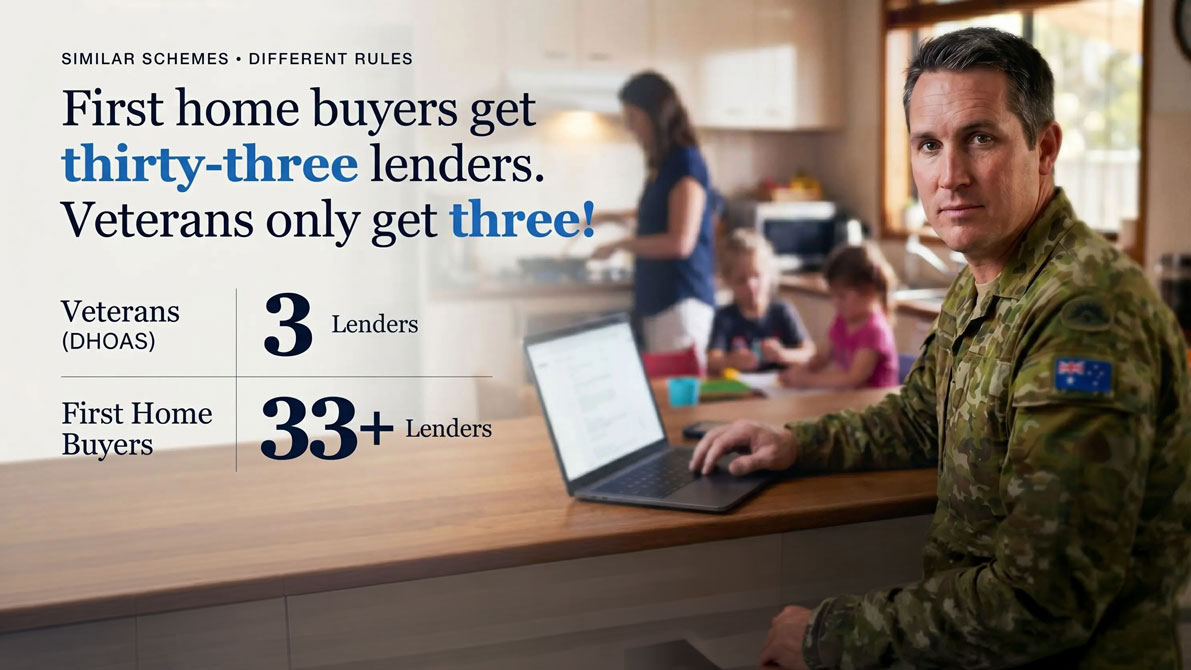
- 26 May 2026. The Shadow Minister for Defence Industry and Defence Personnel, Phillip Thompson OAM MP, raised DHOAS reform in the Federation Chamber, noting that first home buyers choose from 33 lenders under the Commonwealth scheme while veterans get three.
- 27 May 2026. The campaign was covered by Defence Connect and The Adviser.
- 29 May 2026. realestate.com.au reported that veterans are being forced to pay up to $100,000 extra on their home loans.
- 2 June 2026. Independent Senator David Pocock put our figures to the Department of Defence at Senate Estimates. The questions were taken on notice.
- Network 10 News ran a segment on the closed panel featuring Stanford Financial's founder Logan Stanford, the Minister for Veterans' Affairs and veterans directly affected by the scheme.
What we are asking for
Two changes, neither of which requires legislation. Accreditation opens to any lender that meets published criteria, and rate parity is written into the panel deeds of agreement so a DHOAS borrower is offered the same owner-occupier rate the lender would offer anyone else. Housing Australia already administers the First Home Guarantee on that model across 33 accredited lenders. The subsidy formula under sections 49 to 53 of the DHOAS Act does not change, so the Commonwealth's cost does not change either. What changes is how much of the subsidy reaches the member.
Where to follow the campaign
We keep the DHOAS reform page current as each development lands, including the parliamentary record, the media coverage and the state of the AusTender procurement that appoints the next panel.
If you have served, or are serving
Stanford Financial acts for ADF members and veterans on home loan applications, including DHOAS files. If you want to talk through how the current panel affects your own circumstances, or what reform could mean for a loan you already hold or are planning, call us on 0483 980 002 or book a time below.
Who is eligible for DHOAS
ADF members may be eligible for home loan subsidies under the Defence Home Ownership Assistance Scheme. Stanford Financial is accredited with Australian Military Bank, a DHOAS home loan provider, and can assist eligible members to apply for an Australian Military Bank DHOAS home loan. We are unable to confirm your eligibility for DHOAS. For full eligibility criteria, visit dhoas.gov.au or call 1300 434 627.